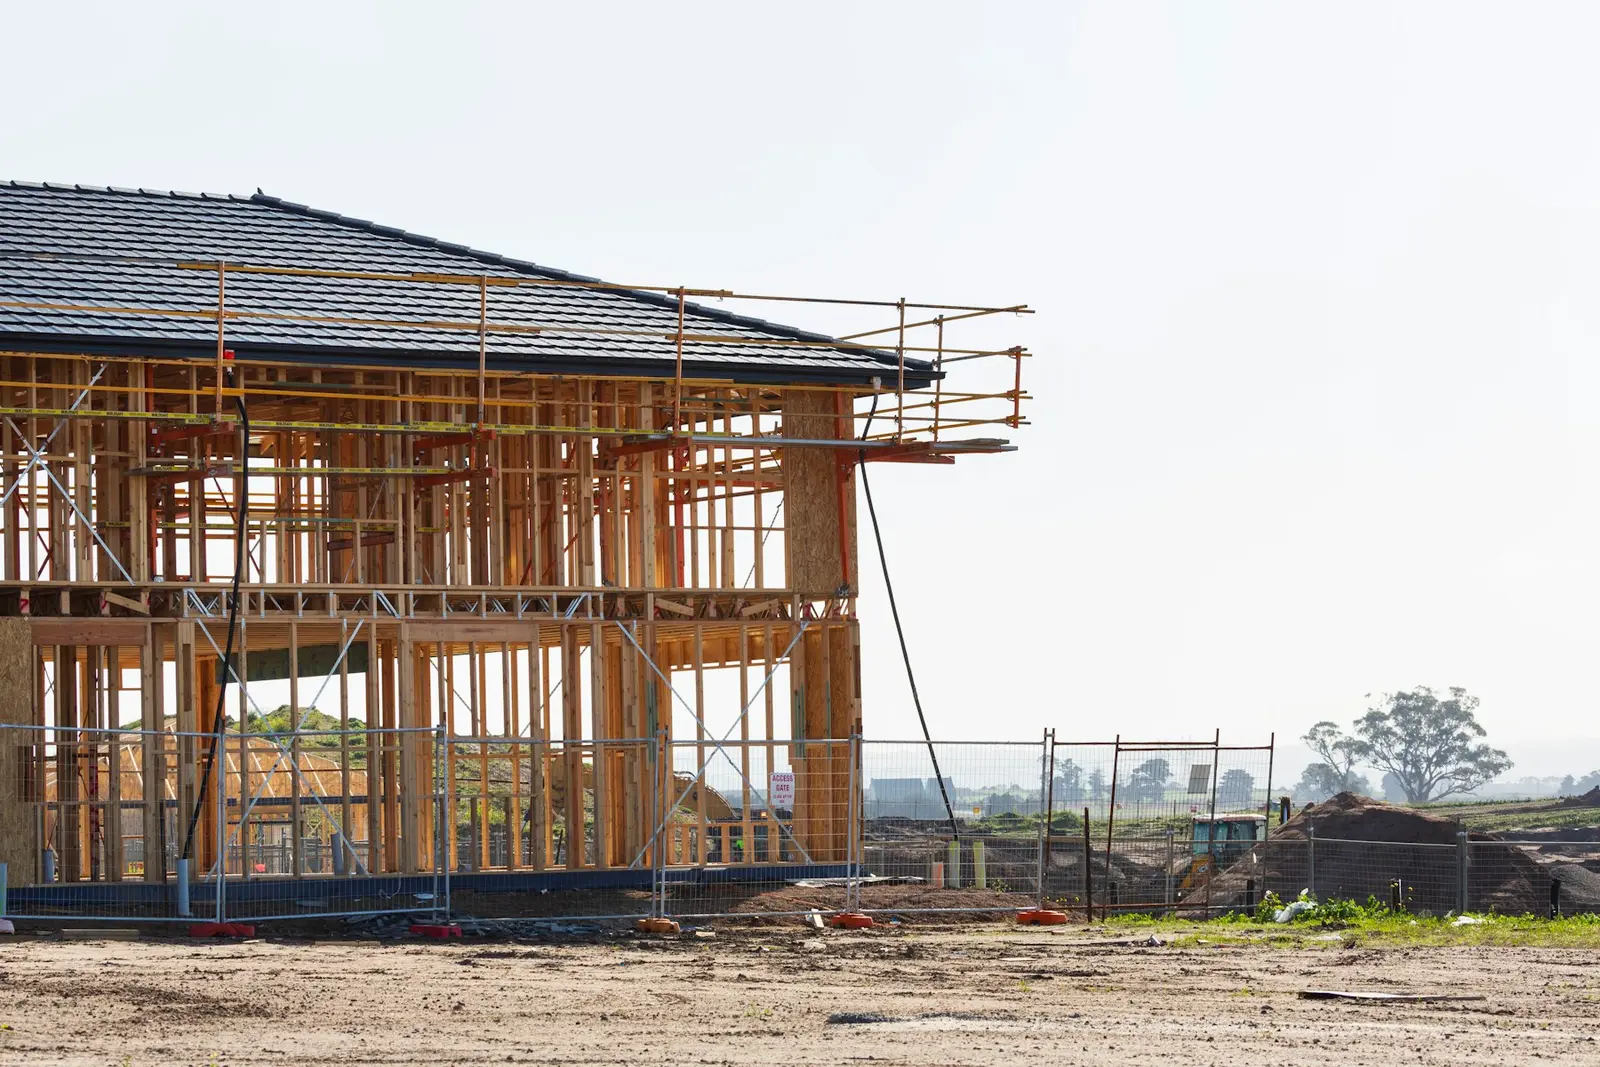
A construction loan isn’t paid out in one go. The lender releases money in stages as your builder completes each part of the job, which protects you and the lender from paying for work that hasn’t been done.
The usual stages
- Deposit, paid when you sign the building contract
- Slab or base
- Frame
- Lock-up, when the windows and external doors are in
- Fixing, for internal fit-out
- Practical completion
What you pay during the build
Most construction loans charge interest only on the amount drawn so far, so repayments start small and grow as the build progresses. Once the home is finished, the loan usually switches to regular principal and interest repayments.
Avoiding delays
Each stage usually needs the builder’s invoice and sometimes a lender inspection before payment is released. Changes to the plans or contract price can affect your approval, so check with George before agreeing to variations.
This article is general information only and does not take into account your objectives, financial situation or needs. It is not credit advice. Credit Representative 406032 is authorised under Australian Credit Licence 384408. Australian Credit Licence 384408 is held by Elders Home Loans Pty Ltd (ABN 22 118 064 654).
Let’s talk about your next move.
Leave your details and George will call you at a time that suits you.